Library / Backtest overfitting
Deflated Sharpe Ratio (DSR)
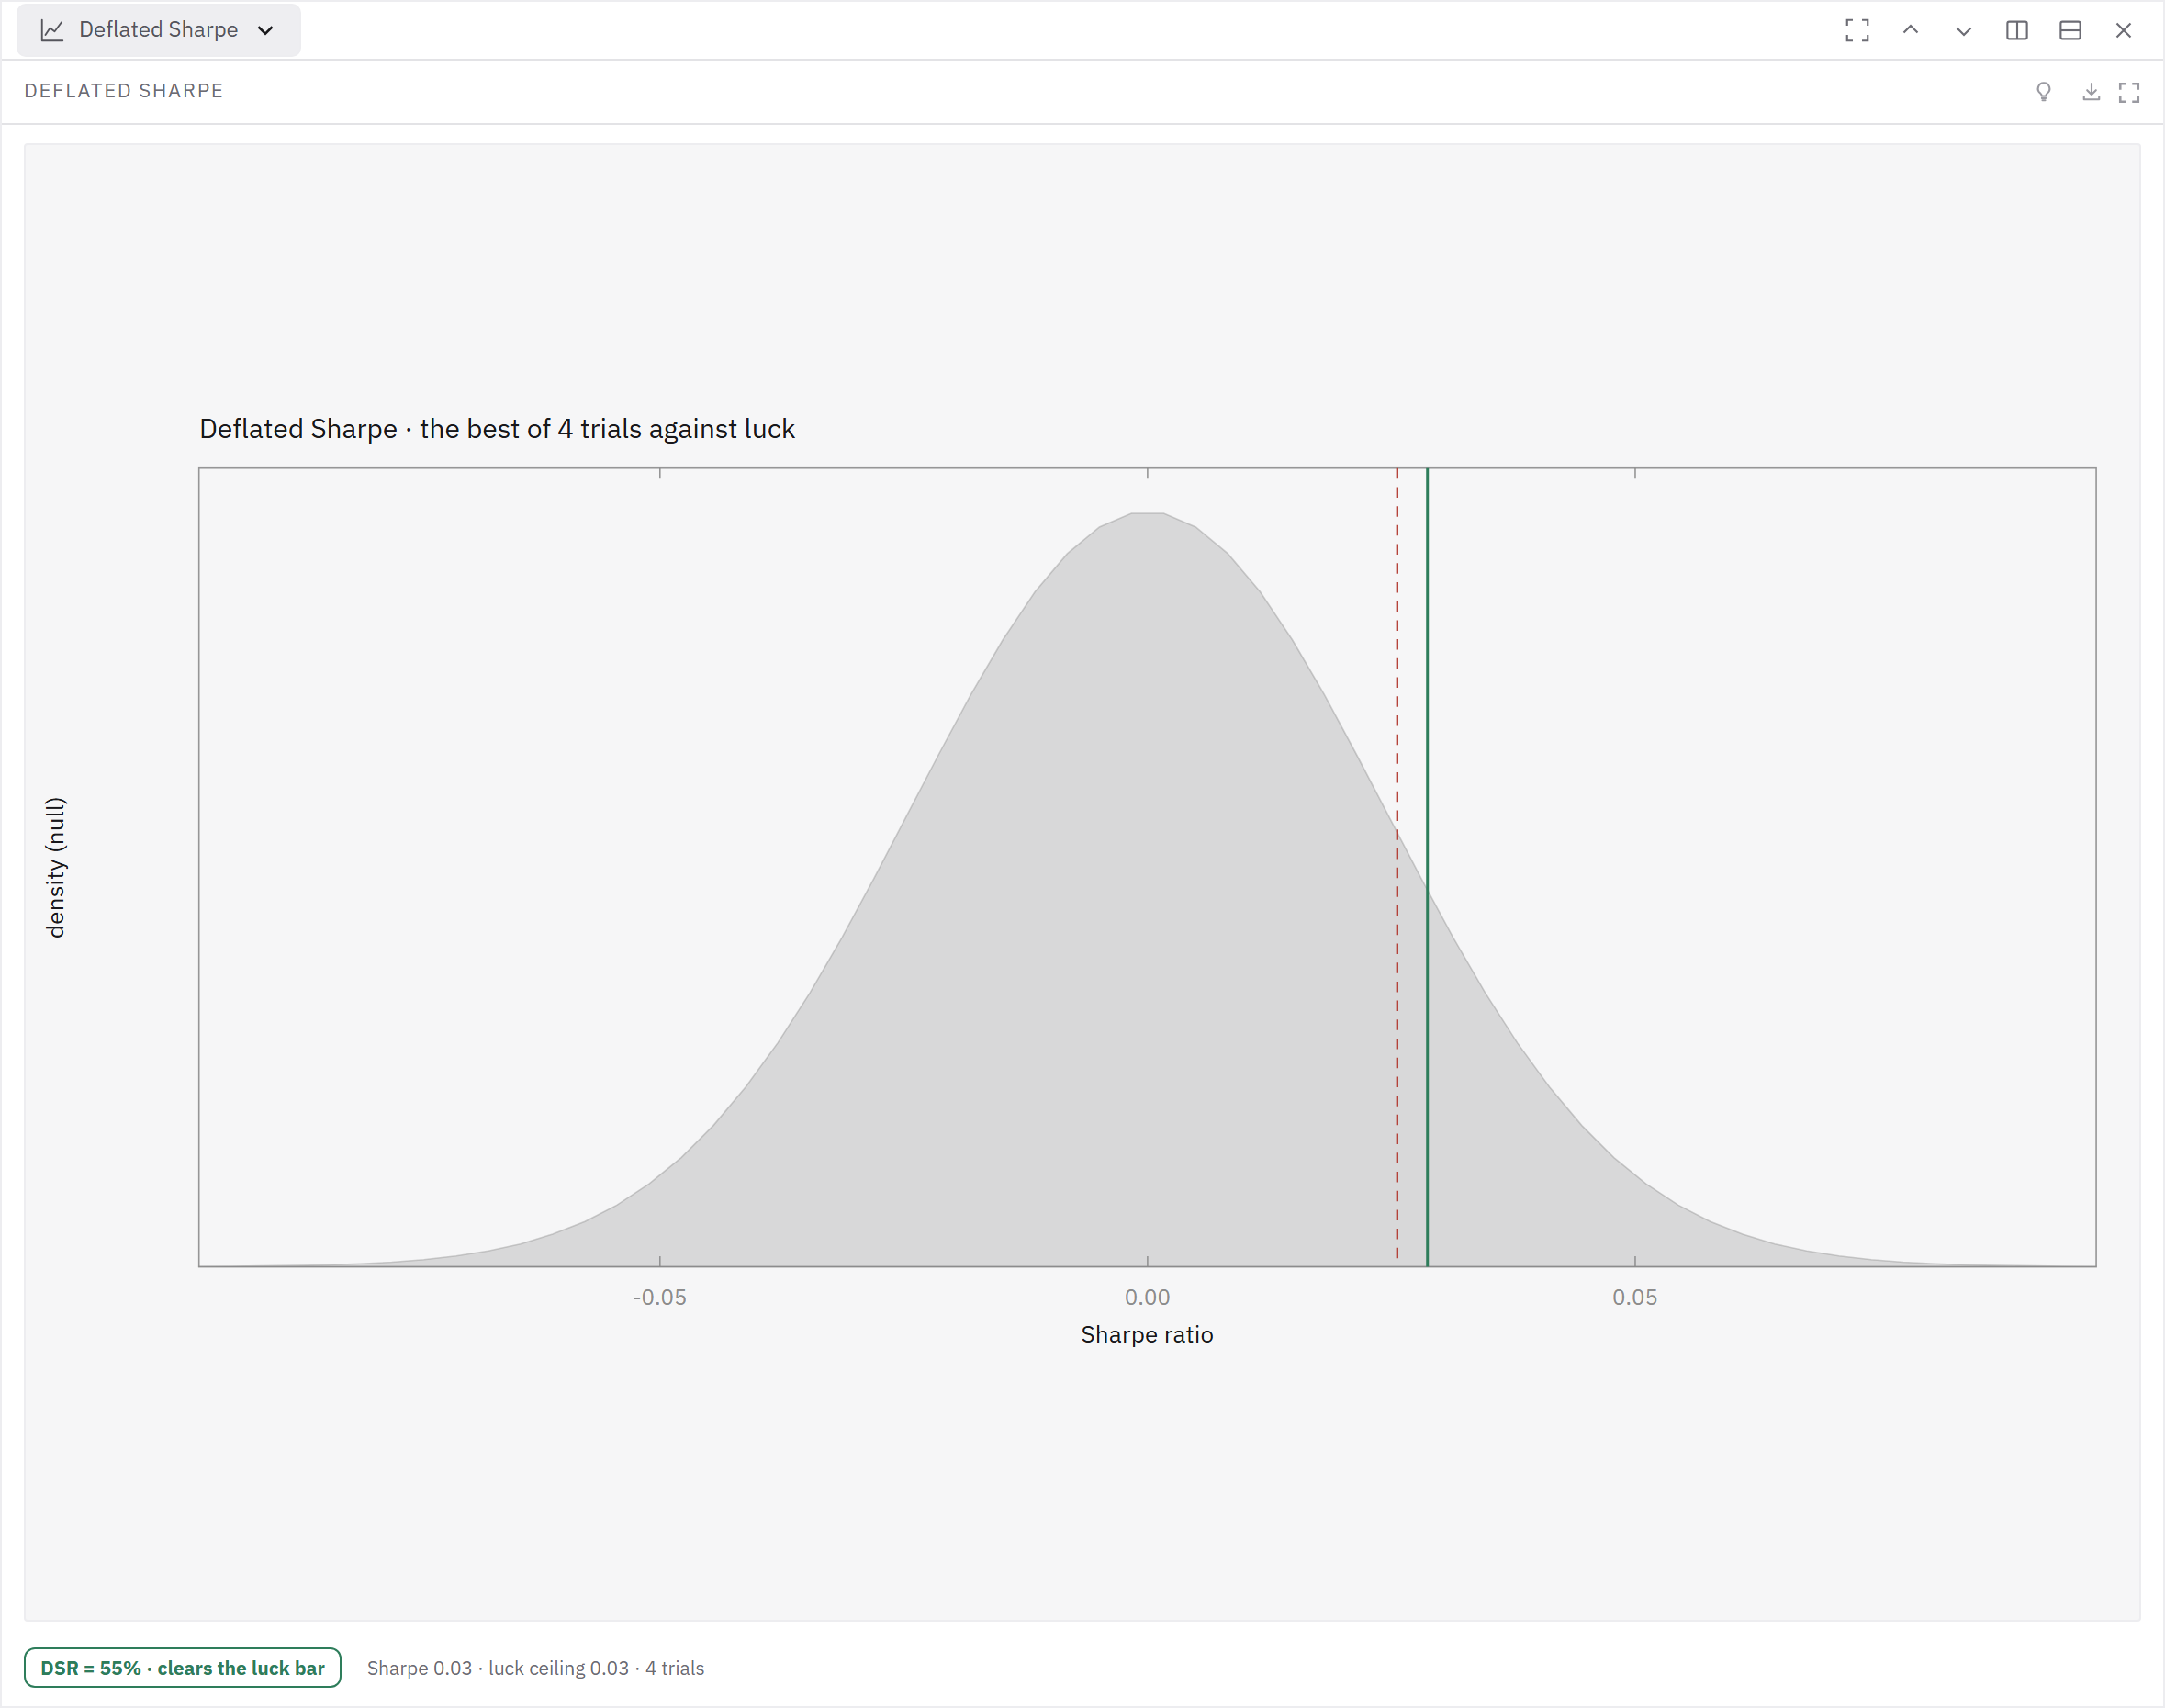
Evidence map
| Aspect | Finding |
|---|---|
| What it is | The Probabilistic Sharpe Ratio evaluated against a benchmark SR₀ that is not zero but the expected maximum Sharpe achievable by chance across N trials — deflating an observed Sharpe for multiple testing, sample length, and non-normality simultaneously. |
| Key result / formula | DSR = Φ( (SR̂ − SR₀)·√(n−1) / √(1 − γ₃·SR̂ + ((γ₄−1)/4)·SR̂²) ), with the multiple-testing benchmark SR₀ = √V · [ (1−γ)·Z⁻¹(1 − 1/N) + γ·Z⁻¹(1 − 1/(N·e)) ], where V = variance of the trial Sharpe ratios, N = number of trials, γ ≈ 0.5772 (Euler–Mascheroni), Z⁻¹ = inverse normal CDF, SR̂ non-annualized. DSR > 0.95 ⇒ the strategy beats the multiple-testing null with 95% confidence. |
| Why it matters for backtesting | A raw Sharpe is meaningless without N and V. |
Why it matters for backtesting
DSR is the practical antidote to backtest overfitting: it shrinks Sharpes discovered after many trials toward the noise floor. Many "1.5 Sharpe" backtests collapse under DSR once N is counted in full — the correct null is "beat SR₀", not "beat zero".
Worked check
A daily Sharpe of 0.10 over 252 independent days has a rough annualized value of 0.10 × sqrt(252) ≈ 1.59. That calculation says nothing about how many alternatives were tried. DSR instead evaluates the observed Sharpe against an expected maximum under a stated effective trial count, with a standard error affected by sample length, skew and kurtosis. Entering one trial after a sweep of 100 configurations understates the selection hurdle. Conversely, treating 100 nearly identical windows as 100 independent trials overstates it. Report the trial population and its dependence estimate. A DSR probability measures evidence conditional on those inputs; it is not a forecast of live returns or a correction for stale data and costs.
Source
Bailey & López de Prado, "The Deflated Sharpe Ratio: Correcting for Selection Bias, Backtest Overfitting, and Non-Normality", Journal of Portfolio Management 40(5), 2014, pp. 94–107 (SSRN 2460551).